What Is the Step-by-Step Process to Buy a House in Ireland?
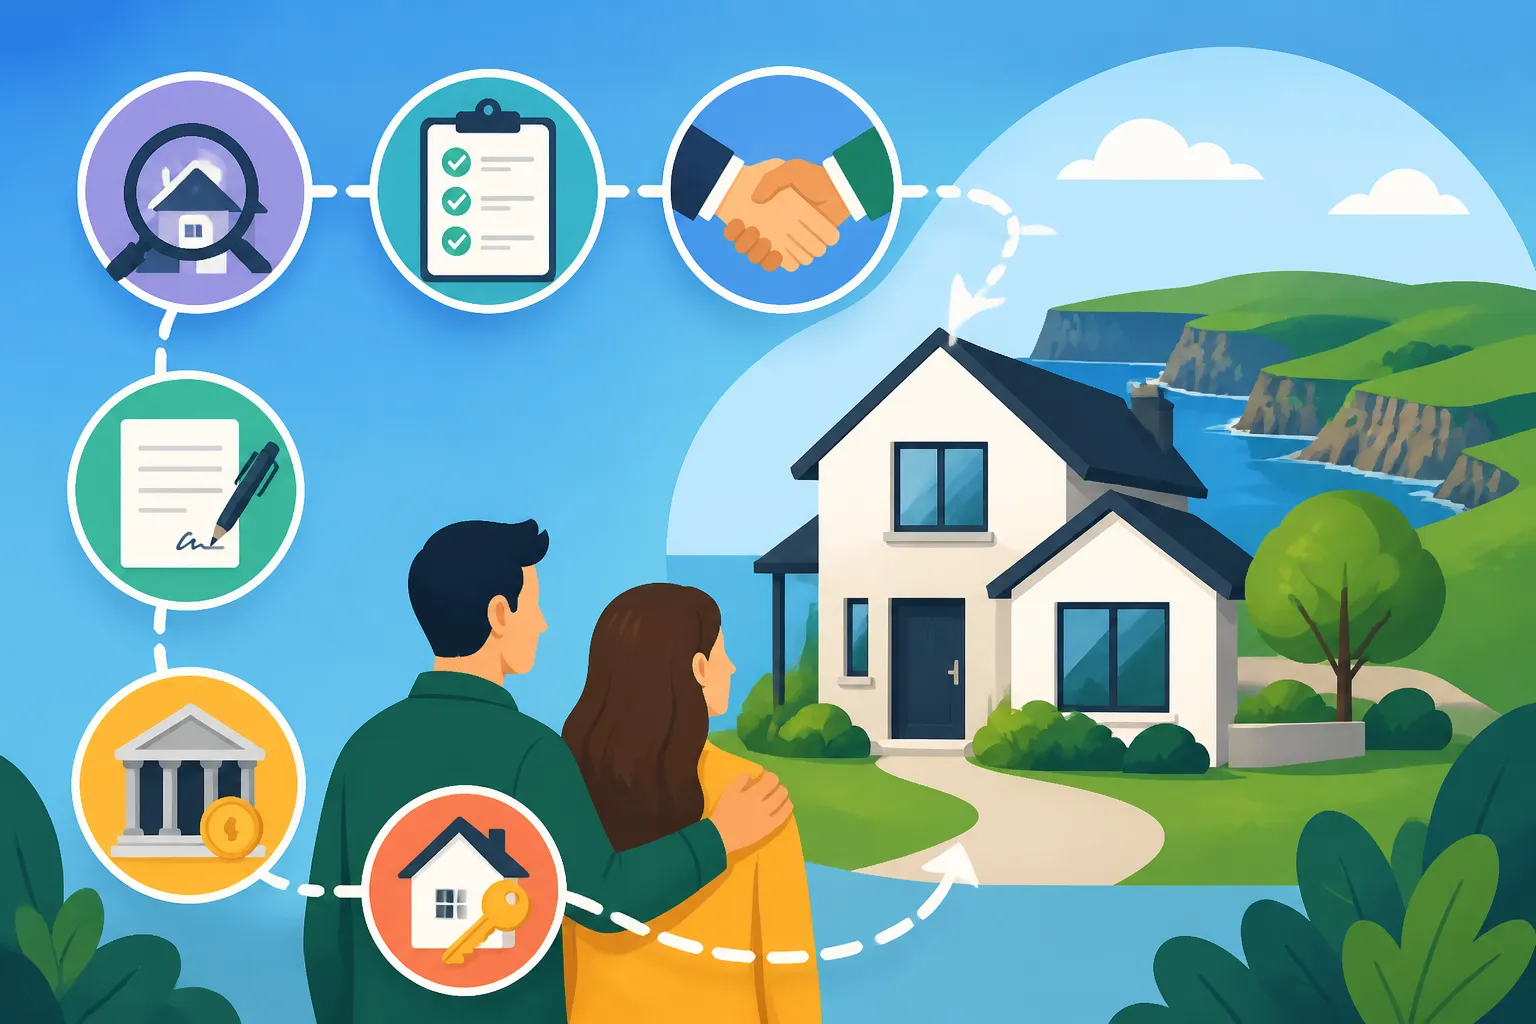
Moving to Ireland can feel like stepping into a dream, with its stunning landscapes, vibrant culture, and friendly faces. But when that dream turns to the practical reality of buying a house here, many expats, myself included, quickly realise it's a journey fraught with unique challenges, often feeling like an uphill battle through a bureaucratic maze. This guide is here to walk you, step-by-weary-but-ultimately-rewarding-step, through the often-confusing process of buying a home in Ireland, from getting your finances in order to finally holding those coveted keys.
The Initial Hurdles: Financial Planning and Eligibility
Before you even start dreaming about a quaint cottage in Kerry or a chic apartment in Dublin, you need to get your financial ducks in a row. This is often where the reality check hits hardest for many newcomers, as the Irish property market has its own set of rules and expectations, especially when it comes to borrowing.
Understanding Mortgage Eligibility and the Central Bank Rules
First things first: the Central Bank of Ireland has strict lending rules, and they apply to everyone, locals and expats alike. These rules are designed to protect both you and the lenders, but they can feel incredibly restrictive when you're trying to get on the property ladder. The two main ones you'll contend with are the Loan-to-Value (LTV) and Loan-to-Income (LTI) limits.
For first-time buyers, the LTV is generally capped at 90%, meaning you need at least a 10% deposit of the property's value. For subsequent buyers, it drops to 80%, requiring a hefty 20% deposit. This is a significant chunk of change, and saving it up while paying Irish rent – which, let's be honest, can be eye-watering – is a monumental task. I remember friends stressing over every penny, foregoing holidays and even small luxuries just to hit that deposit target. Then there's the LTI limit, which means you can typically borrow no more than 3.5 times your gross annual income. This applies to your combined income if you're buying with a partner. For example, if you earn €60,000, your maximum mortgage could be €210,000. It quickly becomes clear why many people struggle to afford property in high-cost areas like Dublin. These rules are non-negotiable, and lenders are obligated to adhere to them. It’s crucial to understand these limits from the outset, as they dictate your budget. You might find it helpful to delve deeper into Understanding Mortgage Rules and the Central Bank Limits in Ireland to get a full grasp of what you're up against.
Securing Your Finances: Mortgages and Pre-Approval
Once you understand the landscape, the next logical step is to secure your financing. This usually begins with getting mortgage pre-approval. This isn't a final offer, but it’s a strong indication from a lender of how much they're willing to lend you based on your financial situation. It’s absolutely essential before you start seriously looking at properties, as estate agents will often ask if you have pre-approval, and it shows sellers you're a serious buyer.
The process of getting pre-approval can be quite detailed. You'll need to provide a treasure trove of documents: several months of payslips, bank statements (for all your accounts, not just the main one!), proof of your PPSN (Personal Public Service Number), and often an employment letter from your current employer. If you’ve got any outstanding loans or credit card debt, they’ll want to see statements for those too. For expats, especially those with income from abroad or a shorter work history in Ireland, this can sometimes take a bit longer. Lenders want to see a stable employment history and consistent savings. Don't be surprised if they ask for explanations for any unusual transactions or gaps in employment. It's all part of their risk assessment. While navigating the financial system can be daunting, a good mortgage broker can be a godsend here, as they work with multiple lenders and can guide you through the paperwork. For a broader overview of how banking works here, check out Banking in Ireland: A Complete Guide for Foreigners (2027).
The Help to Buy Scheme: Is It for Expats?
Ireland, like many countries, has schemes designed to help first-time buyers get on the property ladder. The Help to Buy (HTB) scheme is one such initiative, offering a tax refund to eligible first-time buyers to help with the deposit for new homes or self-builds. It sounds fantastic, doesn't it? But, like all government schemes, there are specific eligibility criteria.
To qualify for HTB, you must be a first-time buyer, meaning you cannot have previously purchased or built a home in Ireland or anywhere else. The property must be your primary residence, and it needs to be a new build or a self-build. The maximum relief available is €30,000 or 10% of the property's value, whichever is lower. For expats, the main hurdle can sometimes be the tax residency requirement, as you generally need to be tax resident in Ireland for certain periods to fully benefit from the scheme. However, if you've been working and paying tax in Ireland for a while and meet all other criteria, it could potentially reduce the amount you need to save for your deposit. It’s always best to check the most current Revenue guidelines, or speak with a qualified financial advisor who understands the intricacies for non-Irish nationals. For a detailed look, you can read more about Understanding the Help to Buy and First Home Schemes in Ireland.
The Hunt and the Bid: Finding Your Dream Home
Once you have your pre-approval in hand, the real fun (and often, stress!) begins: finding a property and making an offer. This stage requires patience, a keen eye, and a thick skin, especially in a competitive market like Ireland's.
Navigating the Property Market: Research and Viewings
The vast majority of properties for sale in Ireland are listed on two main websites: Daft.ie and MyHome.ie. These will become your new best friends (or worst enemies, depending on the day!). You'll spend hours scrolling, filtering, and analysing. It’s an exercise in balancing your budget with your wish list, and often, compromising.
When you're viewing properties, don't be afraid to ask questions. Lots of them. How long has it been on the market? Why are the current owners selling? What's the area like for transport, schools, and local amenities? For expats, understanding the nuances of different neighbourhoods can be tricky. A place that looks great on paper might be a pain for commuting, or lack the community feel you're looking for. This is where local knowledge truly shines. Engaging with estate agents can be beneficial, as they often have insights into properties before they hit the major portals. They can also advise on typical pricing in specific areas. However, remember they work for the seller, so always take their advice with a pinch of salt and do your own research. If you're pondering where to settle, The Best Places to Live in Ireland for Expats: A Complete Guide (2027) might offer some valuable perspectives.
The viewing process itself can be a bit of a whirlwind. Open viewings can be packed, with queues out the door, especially for attractive properties in desirable areas. This can be disheartening, making you feel like you're in a race against time. Try to attend as many viewings as possible to get a feel for the market, what your money buys you, and what compromises you’re willing to make. And while you're out and about, keeping connected is key. If you're relying on public Wi-Fi or struggling with your existing phone plan, a reliable eSIM from providers like Airalo can ensure you're always online to check new listings or coordinate with estate agents without racking up huge roaming charges.
Making an Offer and Going 'Sale Agreed'
So, you've found a place you love. Now comes the nail-biting part: making an offer. In Ireland, offers are typically made through the estate agent, either verbally or in writing. It's often an iterative process, with the agent relaying higher bids back and forth until the seller accepts one. Don't feel pressured to go over your budget, but be prepared for some back-and-forth, especially if it's a popular property.
Once your offer is accepted, the property is typically marked "sale agreed." This is a huge milestone, and you'll likely feel a massive sense of relief. However, and this is crucial, "sale agreed" is not legally binding in Ireland. Until contracts are formally signed, either party can pull out without penalty. This is a source of immense frustration for buyers, as it means you could technically be gazumped (another buyer offering more) even after your offer has been accepted. It's not common practice for ethical agents to encourage gazumping, but it does happen. My advice? Move quickly to the next steps.
Here’s a quick overview of what "offer accepted" and "sale agreed" generally imply:
| Stage | Description | Legal Status | Next Steps |
|---|---|---|---|
| Offer Accepted | Seller verbally or informally agrees to your proposed price. | Not legally binding | Formally instruct solicitors, inform mortgage provider. |
| Sale Agreed | Estate agent confirms offer accepted, typically marks property as such on portals. | Not legally binding | Solicitor begins conveyancing, survey arranged, formal mortgage application. |
As soon as you’re "sale agreed," you need to immediately inform your mortgage provider (to start the formal application process) and, most importantly, appoint a solicitor specialising in conveyancing.
Finding the Right Professional Team
Buying a house in Ireland is not a solo endeavour; you need a crack team of professionals behind you.
First up, a good solicitor is non-negotiable. They will handle all the legal aspects of the property transfer, known as conveyancing. Don't skimp here. A diligent solicitor can spot potential issues with the property's title, ensure all planning permissions are in order, and protect your interests. Ask for recommendations, check reviews, and get clear quotes. You'll be communicating with them constantly, so find someone you trust and feel comfortable with. For more insights on this critical step, refer to How to Complete the Conveyancing Process When Buying in Ireland.
Secondly, you'll need a surveyor or engineer. Before you sign anything legally binding, it’s absolutely vital to get an independent structural survey of the property. This professional will check for issues like damp, structural problems, roof condition, and anything else that could be a costly problem down the line. They are your eyes and ears, identifying defects that aren't obvious to the untrained eye. This survey report can also be a valuable tool for renegotiation if significant issues are uncovered.
While these professionals are handling the specifics of the purchase, remember the bigger picture. Moving to a new country and a new home involves a lot of logistics. This is where services like Sirelo can be incredibly helpful. They act as a platform to compare quotes from various international removal companies, which takes a huge load off your shoulders when planning how to get all your worldly possessions to your new Irish abode.
The Legal Maze: Conveyancing and Closing
Once your offer is accepted and you have your legal and surveying teams in place, you enter the conveyancing phase. This is arguably the most complex and time-consuming part of buying a house in Ireland.
The Conveyancing Process: What Your Solicitor Does
Your solicitor will now swing into action. Their job is to ensure that the property's title is sound and that there are no nasty surprises waiting for you after you purchase it. This involves a detailed investigation of the property's history, known as "title checks." They'll scrutinise the deeds, check for rights of way, easements, and any covenants that might affect your use of the property.
They will also exchange contracts with the seller's solicitor. This begins with them receiving the "contract for sale," a hefty document that outlines the terms of the sale. Your solicitor will then raise "pre-contract enquiries" (questions about the property, boundaries, services, etc.) and "requisitions on title" (questions specifically about the legal ownership). This back-and-forth can take weeks, sometimes months, as solicitors clarify details, request missing documents, and iron out any discrepancies. This is often the stage where delays occur, and it requires a great deal of patience. I recall a friend whose purchase was held up for weeks over a missing planning permission document from 30 years ago! It feels incredibly slow, but it's vital work to protect your investment.
Getting Your Survey Done and Addressing Issues
While the legal eagles are doing their thing, your surveyor or engineer will conduct the pre-purchase inspection. This is a comprehensive check of the property from top to bottom. They'll look at the structure, roof, plumbing, electrics (though they won't typically test appliances), insulation, and drainage.
The surveyor's report will detail any defects found, categorising them by severity. Minor issues like a dripping tap or a bit of cracked plaster are common. However, if they uncover major problems like subsidence, extensive damp, or a failing roof, you have options. You can use this information to:
- Renegotiate the price: Ask the seller to reduce the price to cover the cost of repairs.
- Ask the seller to fix the issues: Although this is less common and can delay the sale further.
- Walk away: If the issues are too severe, too costly to fix, or if the seller is unwilling to budge, you have the right to withdraw from the sale at this stage (before contracts are signed).
Always remember that once contracts are signed, you buy the property "as is," so this survey is your last chance to identify and address physical defects.
Signing Contracts and Setting the Closing Date
When your solicitor is satisfied with all the legal aspects and you're happy with the survey results, you'll be called in to sign the contracts. This is a big moment, as it's the point of no return! Once both you and the seller have signed, the contracts are exchanged, and the sale becomes legally binding. At this stage, you'll typically pay a non-refundable deposit (usually 10% of the purchase price, less any booking deposit already paid).
Your solicitor will then coordinate with your mortgage lender to arrange the drawdown of your mortgage funds. They will also calculate all the final payments, including Stamp Duty. Stamp Duty is a tax on property purchases in Ireland, and it's calculated as a percentage of the purchase price (currently 1% on properties up to €1 million, and 2% on the excess). It's a significant additional cost that often catches expats off guard. For a breakdown of all associated costs, including Stamp Duty, you should read Understanding Stamp Duty and Property Taxes in Ireland (2026). A closing date will be set, usually a few weeks after contract exchange, allowing time for the funds to be transferred and for final checks to be made.
Post-Purchase: Getting Settled and Connected
The closing date arrives, and after what feels like an eternity, the house is finally yours! But the journey doesn't quite end there. There's still plenty to do to turn your new property into a real home.
Final Steps: Mortgage Drawdown and Keys in Hand
On the closing day, your solicitor will transfer the remaining funds (from your mortgage and your remaining deposit) to the seller's solicitor. Once this transaction is confirmed, the seller's solicitor will authorise the release of the keys. This is usually done through the estate agent.
Picking up those keys is an incredible feeling of accomplishment, relief, and sheer excitement. It's the culmination of months of hard work, endless paperwork, and probably a few grey hairs. Take a moment to celebrate; you've earned it! The house is officially yours, and the deed of transfer will be registered with the Property Registration Authority of Ireland in your name.
Utility Setup and Getting Connected
One of the first practical tasks you'll face as a new homeowner is getting all your utilities set up. This involves electricity, gas (if your home has it), water (which is managed by Uisce Éireann, though domestic charges are generally covered by general taxation, not direct bills), and waste collection.
You'll need to contact providers like ESB Networks (for electricity connection), various electricity and gas suppliers (e.g., Electric Ireland, Bord Gáis Energy, SSE Airtricity) to set up new accounts. It’s a bit of a dance trying to find the best tariffs, but there are comparison websites like Bonkers.ie that can help you navigate the options. Then there's broadband and TV. Ireland has several providers like Eir, Virgin Media, Sky, and Three, offering different packages depending on your location and needs. For a detailed walkthrough of this often-frustrating process, be sure to check out The Expat Guide to Setting Up Utilities Electricity, Gas, Water in Ireland.
And before your home broadband is even installed, you'll need reliable connectivity. As an expat, I know the pain of arriving in a new place and not having an instant way to connect. This is where an eSIM provider like Airalo can be invaluable. Getting a local data plan instantly on your phone ensures you can call tradespeople, check directions, or even just stream some music while unpacking, without the hassle of finding a physical SIM card.
Moving In and Making It Home
With the utilities sorted, it's time to physically move your life into your new home. If you've shipped your belongings internationally, you'll be coordinating with removal companies. As mentioned earlier, platforms like Sirelo can be extremely useful for comparing reliable international movers and ensuring your possessions arrive safely.
Then comes the fun part: unpacking, furnishing, and decorating to make the space truly yours. Whether you're hitting up IKEA, local furniture shops, or browsing second-hand gems, it's an exciting time. Don't forget the practicalities too: updating your address with all relevant institutions like Revenue, your bank, and your driving licence authority. It might seem like a never-ending list, but each item checked off brings you closer to feeling truly settled. Remember, you’ve just accomplished a huge feat, so take your time and enjoy creating your new life here. For further guidance on those crucial initial months, you can always refer to The Complete Guide to Moving to Ireland: Your First 90 Days (2027).
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute legal, financial, or professional advice. While every effort has been made to ensure accuracy, the Irish property market and legal landscape can change. It is strongly recommended that you consult with qualified legal, financial, and property professionals for advice tailored to your specific situation before making any decisions related to buying property in Ireland.